Best Mortgage Lenders: How to Compare Rates, Fees, and Loan Terms
Delving into Best Mortgage Lenders: How to Compare Rates, Fees, and Loan Terms, this introduction immerses readers in a unique and compelling narrative, with a casual formal language style that is both engaging and thought-provoking from the very first sentence.
Providing clear insights into mortgage lenders, rates, fees, and loan terms, this guide equips readers with essential knowledge to navigate the complexities of the home buying process effectively.
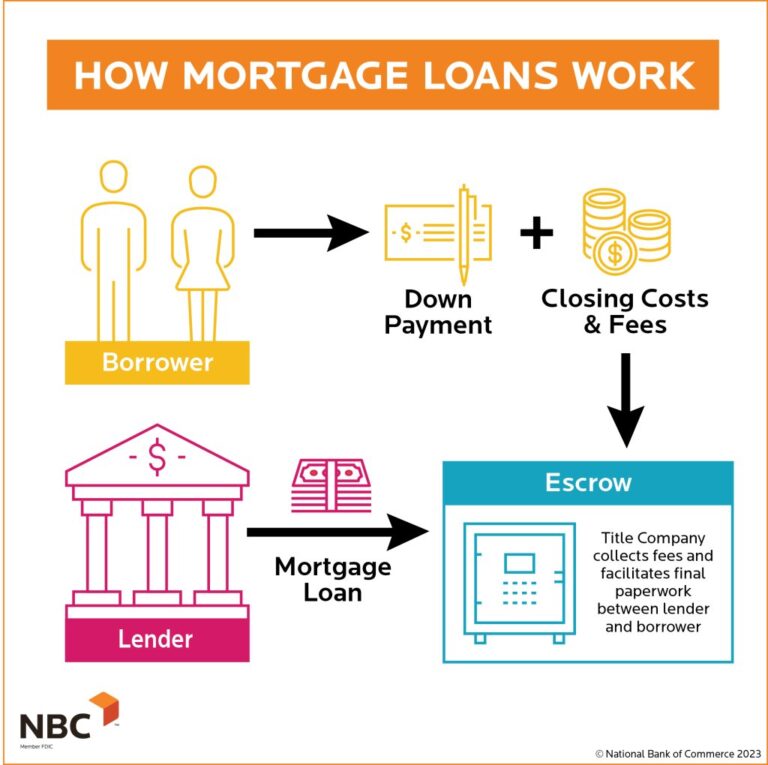
When purchasing a home, most people require financial assistance in the form of a mortgage. Mortgage lenders play a crucial role in providing the funds needed to purchase a home, guiding borrowers through the loan application process, and ultimately approving or denying loan applications.
There are several types of mortgage lenders available to borrowers, each with its own set of advantages and disadvantages. These include:
When looking for a mortgage lender, one of the key factors to consider is the interest rate they offer. Mortgage rates can vary significantly between lenders, so it’s important to understand how they are determined and how to compare them effectively.Mortgage rates are influenced by a variety of factors, including the lender’s cost of funds, market conditions, the borrower’s credit score, and the loan amount.
Lenders will also take into account the type of loan you are applying for, whether it’s a fixed-rate mortgage or an adjustable-rate mortgage.
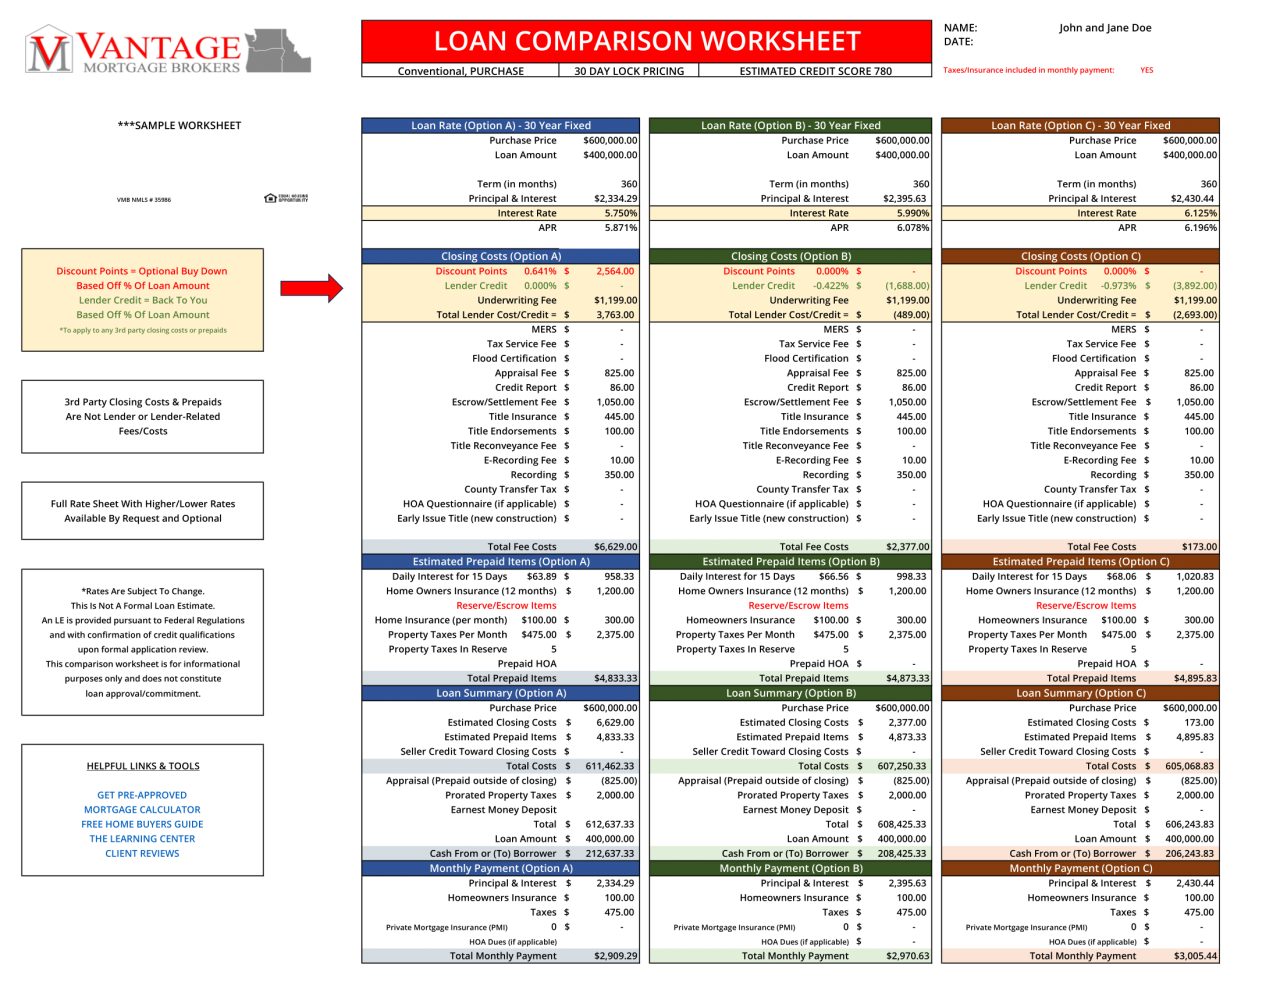
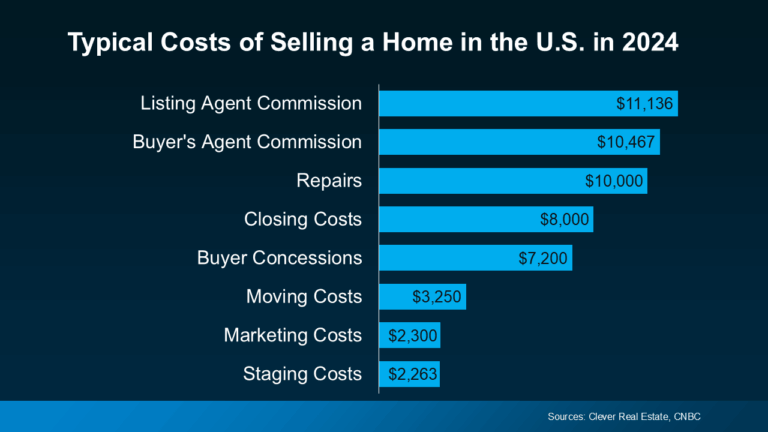
When getting a mortgage, it’s important to consider not just the interest rate, but also the fees and closing costs associated with the loan. Understanding these costs can help you make a more informed decision and potentially save money in the long run.
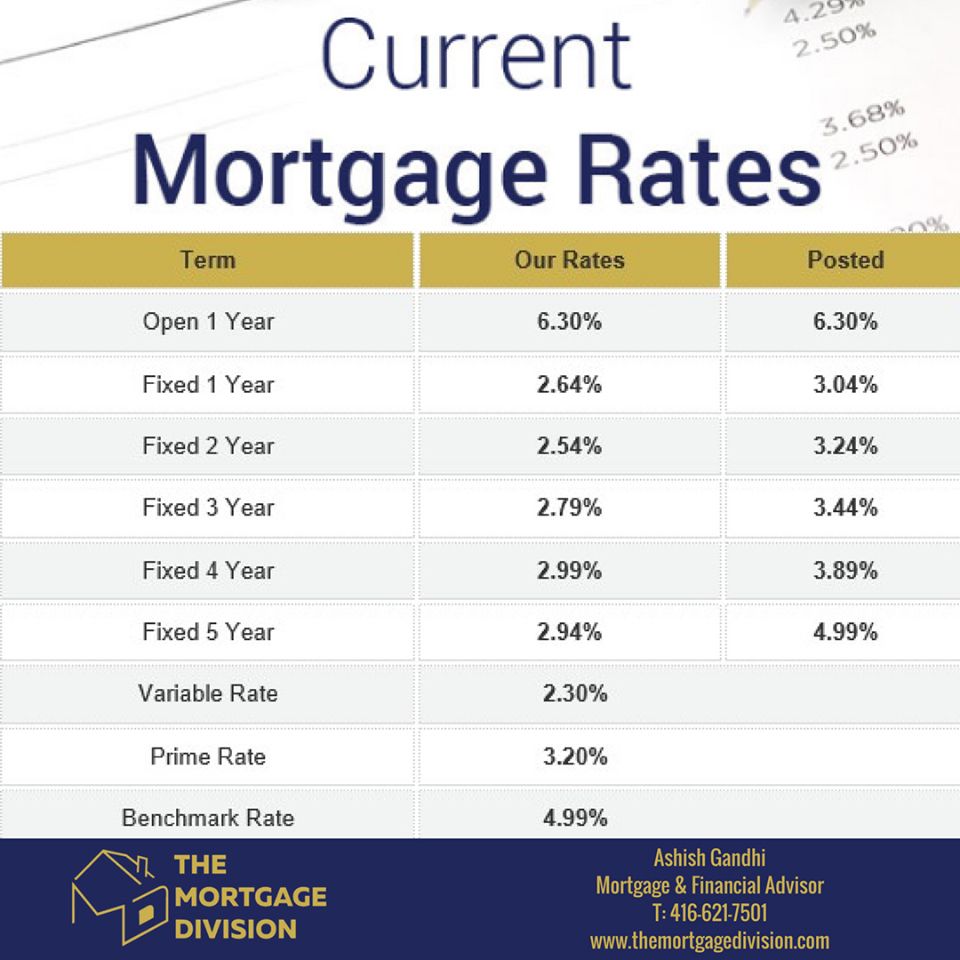
When it comes to securing a mortgage, analyzing the loan terms is crucial in determining the overall cost and affordability of your home loan. Loan terms encompass various key elements that directly impact the amount you will pay over the life of the loan.Loan terms to consider include the loan amount, interest rate, repayment period, and type of interest rate (fixed or adjustable).
Understanding how these factors interact can help you make an informed decision when choosing a mortgage lender.
Understanding how different loan terms can impact overall mortgage affordability is essential for making an informed decision. For example, opting for a shorter repayment period may result in higher monthly payments but lower total interest paid over time. On the other hand, choosing a fixed interest rate provides stability in payments, while an adjustable-rate mortgage can lead to unpredictable changes in monthly payments.
What is the difference between mortgage lenders and mortgage brokers?
Mortgage lenders provide the funds for a loan, while mortgage brokers act as intermediaries between borrowers and lenders, connecting borrowers with suitable loan options from various lenders.
How can I negotiate closing costs with mortgage lenders?
Negotiating closing costs with mortgage lenders involves comparing offers from different lenders, asking for a breakdown of fees, and leveraging your creditworthiness to potentially reduce costs.
What factors should I consider when comparing mortgage rates?
When comparing mortgage rates, consider the type of loan (fixed or adjustable), the interest rate, loan terms, any discount points offered, and the lender’s reputation for customer service and reliability.
How do loan terms impact overall mortgage affordability?
Loan terms such as the loan amount, interest rate, and repayment period significantly affect the total cost of the mortgage and monthly payments, thus influencing the overall affordability of the loan.