Mortgage Calculator: Estimate Monthly Payments, Interest, and Total Cost
Delving into Mortgage Calculator: Estimate Monthly Payments, Interest, and Total Cost, this introduction immerses readers in a unique and compelling narrative, with a casual formal language style that is both engaging and thought-provoking from the very first sentence.
In the realm of financial planning, understanding the intricacies of mortgage calculations is paramount. Whether you’re a first-time homebuyer or a seasoned investor, having a grasp of how mortgage calculators work can make a significant difference in your decision-making process.
This guide aims to demystify the complexities of estimating monthly payments, interest rates, and total costs through the lens of a mortgage calculator. By the end of this exploration, you’ll be equipped with the knowledge to navigate the world of mortgages with confidence and clarity.

A mortgage calculator is a tool designed to help individuals estimate their monthly payments, interest, and total cost when taking out a mortgage loan. By entering specific details such as loan amount, interest rate, and term length, users can quickly get an idea of how much they would need to pay each month and the overall cost of the loan.
When it comes to mortgages, there are several key terms and concepts that borrowers need to understand in order to make informed decisions. Let’s delve into the basics of mortgages and how they impact your monthly payments and total cost.
Several factors influence your monthly mortgage payments and the total cost of your loan:
There are two main types of mortgages based on the interest rate structure:
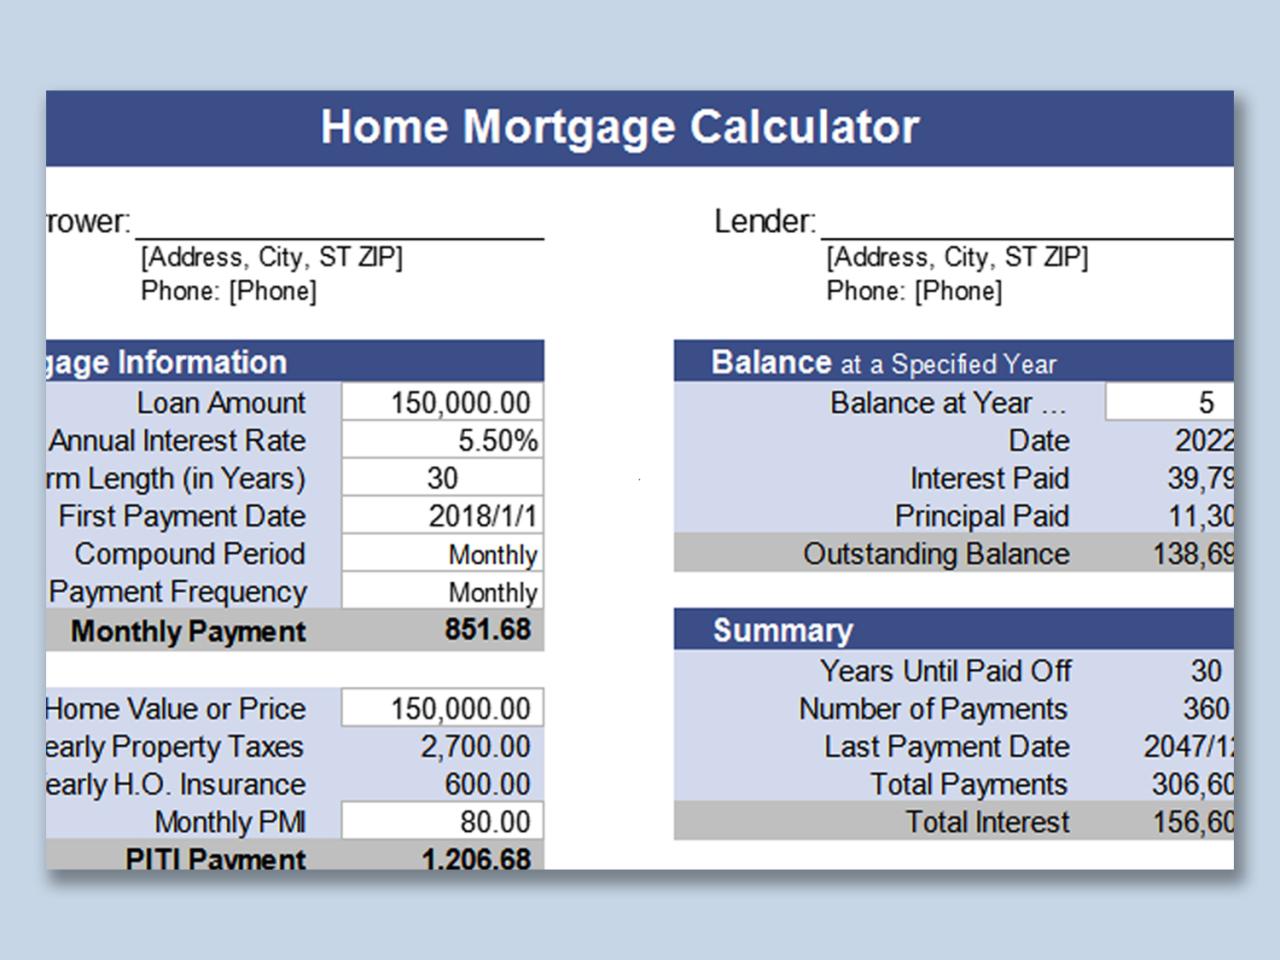
To effectively utilize a mortgage calculator, follow these steps to accurately estimate your monthly payments, interest, and total cost of the loan:
Remember, the results provided by the mortgage calculator are estimates and may vary based on additional factors such as credit score, down payment amount, and lender fees.
When it comes to mortgage payments, several key factors play a significant role in determining the overall cost of a mortgage. Understanding how these factors interact can help borrowers make informed decisions when choosing a mortgage.Changing the loan amount can have a direct impact on monthly payments.
Typically, a higher loan amount will result in higher monthly payments, while a lower loan amount will lead to lower monthly payments. It’s essential for borrowers to consider their budget and financial situation when determining the loan amount to ensure they can comfortably afford the monthly payments.
Interest rates also play a crucial role in the total cost of a mortgage. The interest rate directly affects the amount of interest paid over the life of the loan. A higher interest rate will result in higher total interest costs, increasing the overall cost of the mortgage.
On the other hand, a lower interest rate can lead to significant savings in interest payments over time. Borrowers should shop around for the best interest rates to minimize the total cost of their mortgage.
The loan term, or the length of time over which the loan will be repaid, can also impact the overall cost of the mortgage. Shorter loan terms typically come with higher monthly payments but lower total interest costs. In contrast, longer loan terms may have lower monthly payments but higher total interest costs over the life of the loan.
Borrowers should consider their financial goals and timeline when choosing a loan term to ensure they select the option that best fits their needs.
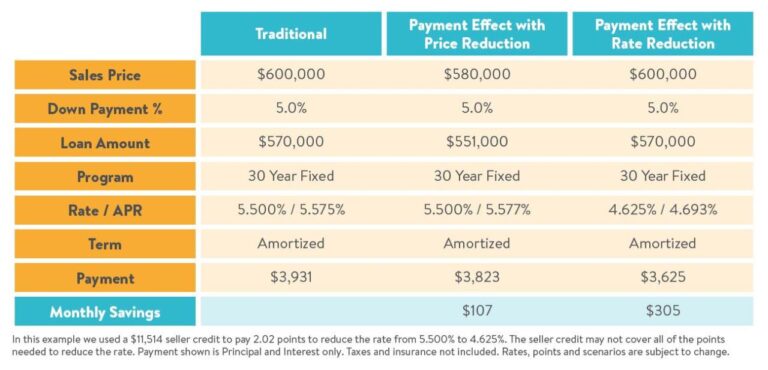
When comparing different mortgage scenarios, it is crucial to analyze how varying loan amounts and interest rates can impact your monthly payments and overall mortgage costs. By using a mortgage calculator, you can easily visualize these differences and make an informed decision based on your financial goals.
Let’s consider a scenario where we compare monthly payments for different loan amounts and interest rates:
Now, let’s analyze how changes in loan terms can affect the total cost of the mortgage over time:
Based on the calculator results, different mortgage scenarios have their own advantages and disadvantages:
It’s important to weigh the pros and cons of each scenario to determine which option aligns best with your financial situation and long-term goals.
Effective mortgage planning involves strategies to minimize interest costs, plan for early loan payoff, and consider additional costs like property taxes and insurance. By following these tips, you can make informed decisions and save money in the long run.
How can a mortgage calculator help in estimating monthly payments?
A mortgage calculator uses key inputs such as loan amount, interest rate, and loan term to provide an estimate of your monthly payments.
What factors influence the total cost of a mortgage?
The total cost of a mortgage is influenced by factors such as the loan amount, interest rate, and loan term.
How do fixed-rate and adjustable-rate mortgages differ?
Fixed-rate mortgages have a constant interest rate throughout the loan term, while adjustable-rate mortgages have interest rates that can fluctuate based on market conditions.
What strategies can be used to minimize interest costs over the loan term?
Strategies such as making extra payments towards the principal and refinancing at lower interest rates can help minimize interest costs over the loan term.
Why is it important to consider additional costs like property taxes and insurance when using a mortgage calculator?
Considering additional costs like property taxes and insurance ensures a more accurate estimate of the overall expenses associated with homeownership.